Tag Archives: investing

Big Semantics continue

I was about to plant a new piece of IP (which will have to wait a day) when some news articles came to me and it gave me additional fodder in the picture my mind had already shaped.

“The media narrative surrounding the AI bubble focuses heavily on whether massive capital expenditures, circular financing deals, and high valuations in artificial intelligence mirror the 2000 dot-com crash or are backed by real revenue. Well, no, most of the media ‘elegantly’ stepped over all that lacking revenue, they did waste time on the expenditure that goes billions over billions. But as I see it, most ‘seemingly forgot’  about return on investment. So as I ‘accused’ these firms of building revenue by paying one another their revenue.“I saw today the image that was unable to make (lack of resources and lack of interest).”
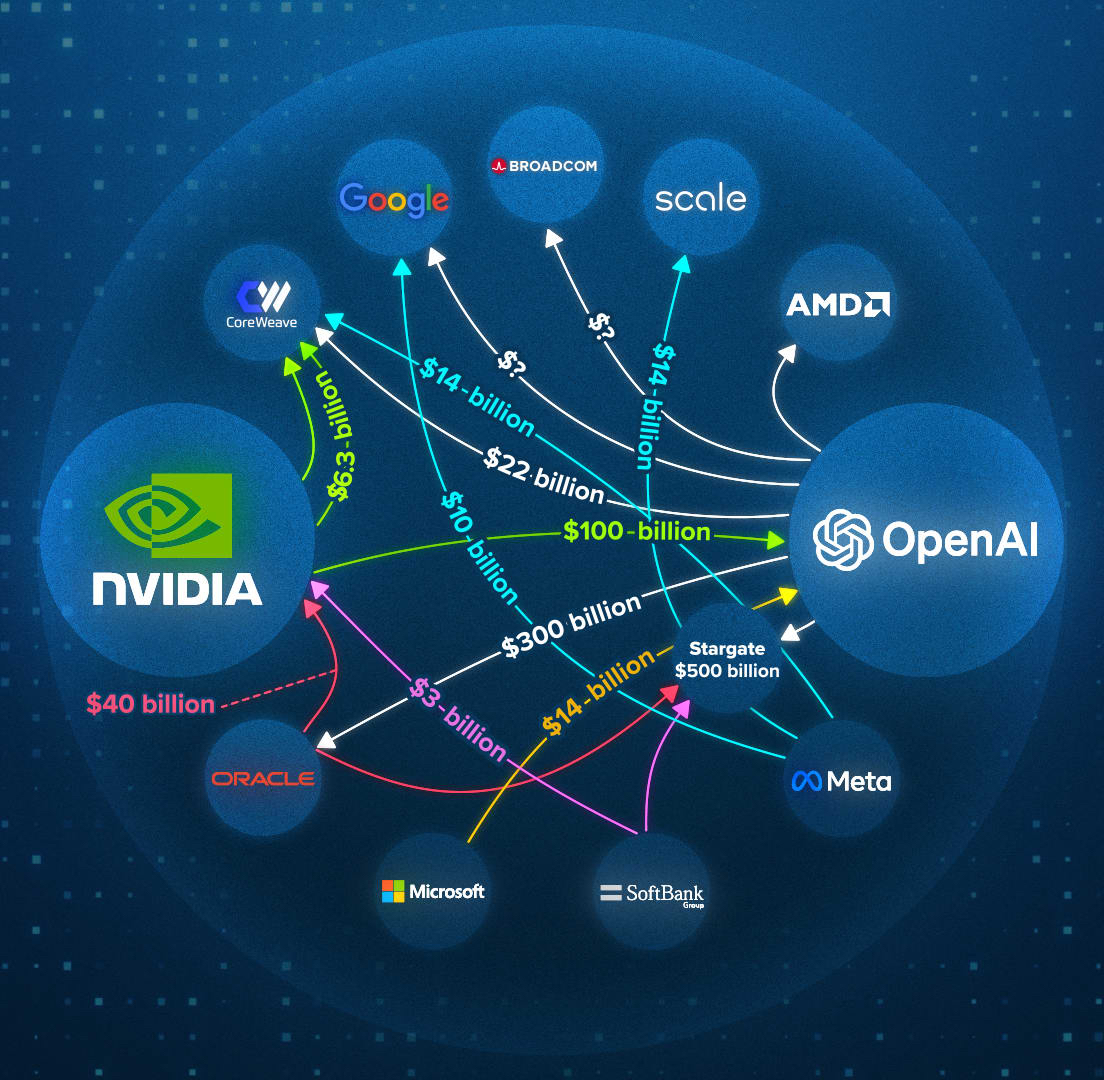
Because if all that is counted as revenue for these companies, the US economy is in a worse state than we think it is (but that could be my wrongful view). Because this implies that the bulk of the US Economy is in merely 11 companies. So where are the other trillions? And if there are people who have critique on all this and my views. That is fair, my view is not an economic view. I merely see the I bubble for what it is, it is fake AI, not real as such that bubble is bursting in a really fake way. So when we get to “Major institutional voices (Goldman Sachs, Morgan Stanley, JPMorgan) and financial analyses (such as via Fidelity) counter that unlike the dot-com era, current mega-caps are funding massive capital expenditure out of actual, robust operating cash flow and high profit margins rather than speculative debt. Companies like Nvidia, Alphabet, and Meta continue to post substantial earnings, revenue growth, and hardware demand (such as high-bandwidth memory chips), though debates persist over whether the returns will justify the trillion-dollar multi-year buildout.” So whilst we see “unlike the dot-com era, current mega-caps are funding massive capital expenditure out of actual, robust operating cash flow and high profit margins rather than speculative debt” As I see it, the shenanigans that Oracle is pulling debates that view, it is a mere struggle to keep themselves on the right sight of the books. So as we are given “Investors wipe $2.5 trillion off Nasdaq”, so what is this? A balancing write off? (Source: Reuters) all whilst some other sources give us that “$2.3 trillion in market value wiped out” but the message is kinda clear. The bubble is bursting and no matter how you want to hide behind the infidelity of one person, there is a rather large bubble getting slashed because investors are now really scared for their easy life and there is no returning to that easy life.

So as Deutsche Welle comes with ‘Is the AI bubble bursting just as Anthropic goes public?’ (At https://www.dw.com/en/is-the-ai-bubble-bursting-just-as-anthropic-goes-public/a-79896537), so in this age of fake AI, all whilst “Microsoft CEO Satya Nadella stated that 20% to 30% of Microsoft’s code is written by artificial intelligence. He also noted that code acceptance rates for AI suggestions sit around 30% to 40% and are growing steadily” and at this point no one is seeking deeper into the Microsoft 365 and whether this is part of ‘their’ AI setting. And consider that this is merely the first, the more these firms ‘embrace’ their fake AI, the larger the setting that they will repeat themselves and create a while range of zero day issues. So how safe do you feel? Important to notice is that this is MY speculations, so please don’t take my word seriously gospel. I merely worked in IT since 1985, So I have been around the block several times and at present I have no idea where this is going.

So, last week we saw “Last week, after the Democrats secured control of the United States Congress in the midterm elections, technology stocks sold off dramatically, with the Magnificent Seven — including Meta, Apple, Amazon and Tesla — losing more than $1 trillion in value in a single trading day.” Can anyone explain to me how politics can have such an impact on market value?
Screenshot

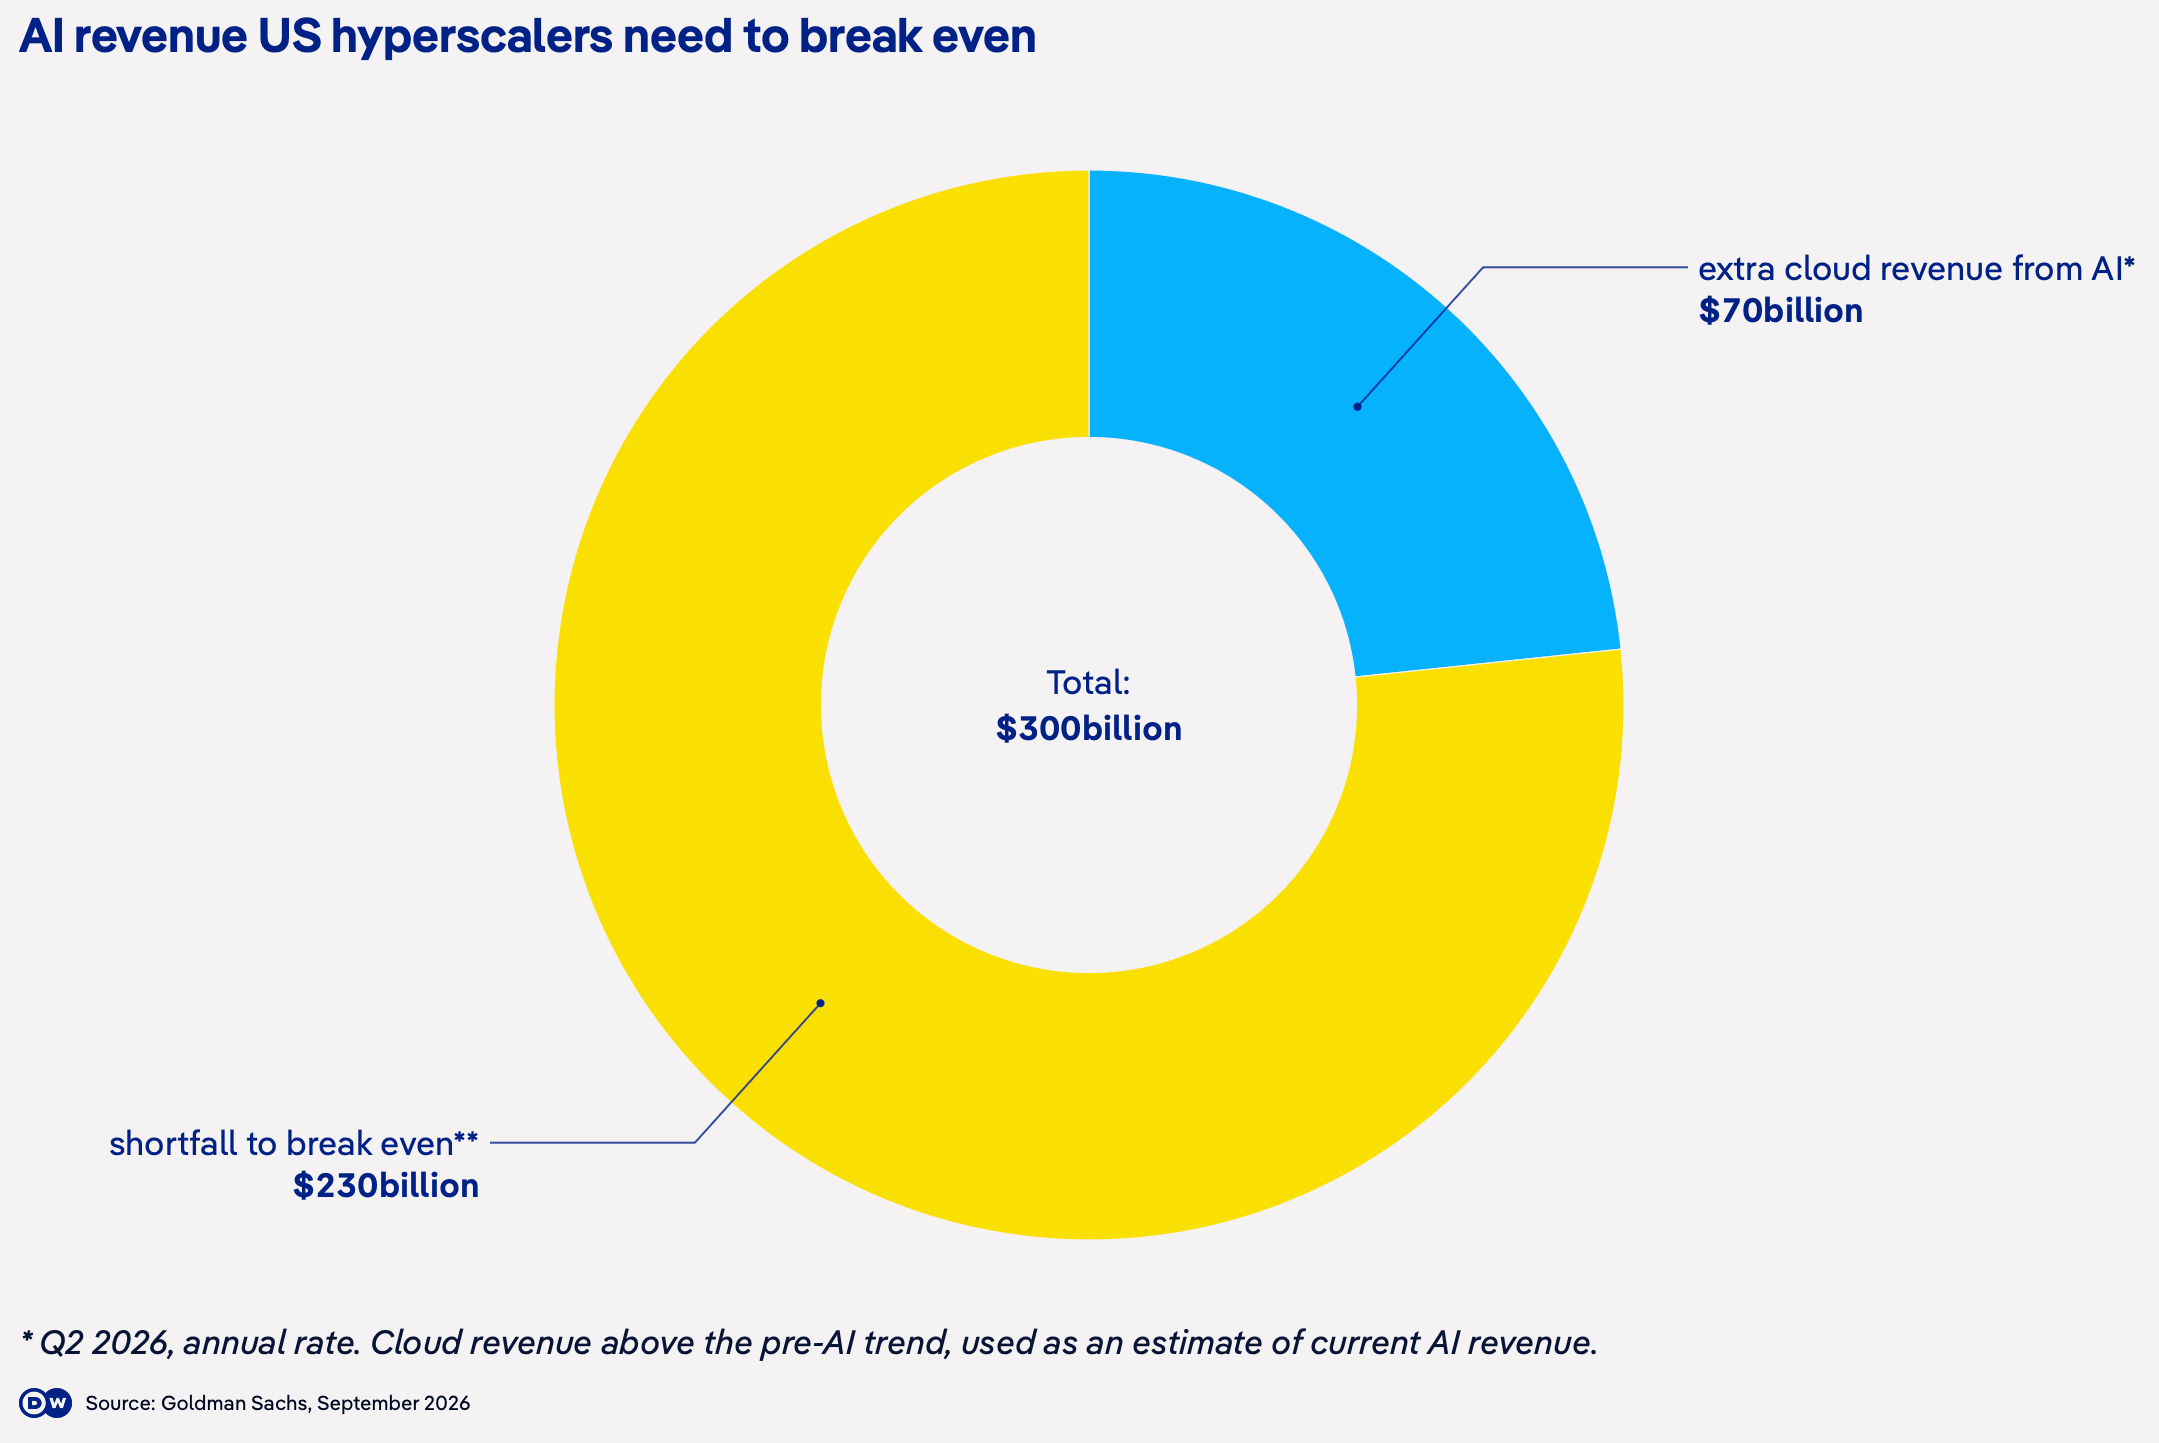
Then they give us this bagel, which shows the ROI setting and these tech forms are a little short, roughly $230B and when you say it fast it doesn’t sound like much, but it also shows that this so called bubble will drain investor of (I reckon) a few trillion more and whilst I have been saying this since January 29th 2025. In ‘And the bubble said ‘Bang’’ (at https://lawlordtobe.com/2025/01/29/and-the-bubble-said-bang/) and it was an earlier ‘write off’ so how many more ‘write off’ moments will we get until someone says the words ‘He have a bubble and it has burst’?

It is a simple question, but as I see it, there are no real winners ate present, only the proclaimers of AI, I have already spoken about that too often and it is tiring. I feel more fun looking at my next article on IP, much more fun. So you all have a great day today.

1 Comment

Filed under Finance, IT, Politics, Science

Decided value

This is a weird article, it is all me, I get that. But when you think of it, the setting we are given does not make sense. So here I was reading the article in the BBC less then an hour ago (at https://www.bbc.com/news/live/c6zjry11v8w1t) where we see ‘Nvidia shares plunge as board reportedly weighs ousting CEO Jensen Huang after second affair allegation’ so business people cut their own wrists as someone has an affair? This is not some affair involving children like Epstein (see the Epstein files). It is allegedly the setting of one adult person shoving his penis into another person of a different gender and they are doing that apparently with consent. As such  its board is ousting its CEO. If that was even really the case around (a speculative) 69% of all CEO’s would be pushed into the street.

So we are getting:

So the guy, the genius behind Nvidia likes sex? That gets him a place that is graced by every man under 40 on the planet. And lets consider Nvidia is (according to some) “Nvidia Corporation is an American multinational technology company headquartered in Santa Clara, California, that designs and sells graphics processing units (GPUs), artificial intelligence (AI) hardware, and computing platforms.” Is anyone accepting this story? Or is it possible that the first signs of an AI bubble are being hidden like a storyline in Peyton Place? So are the 11 board members of Nvidia really these presumed prudes of society, or are they perhaps facing a much worse setting and they are trying to keep safe their ‘earnings’ until they can put it into safe shores? So, whilst we are given in some statistics “Globally, research indicates that around 20% to 23% of married men admit to physical infidelity” the operative word here is ‘admit’. You see, when I was young (a long, long, long time ago) I worked in bars to get by as a student we had a saying over 80% of men are unfaithful, they either already are or they are going to be. There is no exception to that. And in that world Jensen Huang gets happy without Viagra and for that, that firm stocks plummet? How sanctimonious can one get?

As I see it, the AI party is over and the big ones are now shedding their trillions. Nvidia is the likely first, because it is the one dealing in GPUs, a essential part in all that and when AI goes no-one needs GPUs, but if they make it about infidelity, perhaps no one will be looking out of the corner of their eyes to the other firms. That is how I see it.

So, am I right, or am I wrong?

It is a fair question and answering that question reveals where you stand. Would you stomach an infidelity of a man (when it is not your wife) putting trillions at risk, or would you shrug your shoulders silently stating ‘lucky bastard’, because in thousands of places by dozens of women, their are too ‘sexy’ in the mind of some and they are willingly giving it away (consent will at all times be mandatory). You see it hotels and motels keep thorough records of the visitations, too many have going with their wife or husband whist their actual wife or husband is out and about, or slaving in their offices. So when you realise that Nvidia, a firm worth 4.19 trillion, with a market capitalization stands at approximately $4.30 trillion to $4.65 trillion, with shares trading around $170 to $184. It is now $158. This is not about someone being horny, or whatever the BBC is referring to. When it is about that much money it is about something else and as I see it, the arrival of the bursting AI bubble makes a lot more sense.

I’ll let you decide and consider that whilst you are valuing others, others value you too. Because saucer the goose, sauce for the gander is only fair. Now, let it be said that my version is pure speculation, but it is grounded in facts. There has been months of AI bubble speak and as far as

I can tell massively denied by Masayoshi Son (SoftBank) for months. Is this the first pebble that is now plunging in the waves of speculative acceptance of fake AI? And when this comes to blows and AI is seen as fake, will the boards of Amazon, Microsoft, Oracle, Google and Meta realise that they suddenly need a lot more workers than they have? For that matter, when we get to Microsoft with their “Satya Nadella imagines millions of AI agents working with Microsoft’s employees, as Microsoft offers voluntary exits to about 60000 workers.” But here is the rub. You see, as I saw it from the very beginning, there is no AI. It is a mere form of advanced Predictive Analytics. It is a fine tool, but it is a tool and when the inaccuracies and unvalidated data hit those millions of AI agents something will have to give and anyone relying on those AI agents will suddenly see that the workforce they had was doing a lot better and a larger readjustment is needed. As such as I see it, my valuation and those of my peers who are to be in the millions all over the planet are suddenly worth a lot more, because when you do business on unvalidated and unreliable data. Your sales pipeline goes seemingly nowhere.

But what do I know? I am now old and rejected by those smart AI speaking people. What I laugh I’ll have from the sidelines. And they are all boasting to their friends in their Mercedes-Benz with a brand new (younger) girlfriend. So what happens there? I actually do not care. I can just laugh at the sidelines when they impound that car and likely a lot more. That was the impact of a bubble, but who knows. Maybe I was wrong all the time and Masayoshi Son was right. In my reality I am more right then wrong and we are all based on ethical values whilst they all protect the family of Jensen Huang.

You all have a great day today.

Leave a comment

Filed under Finance, IT, Media, Science

Visions

We all have them, they could be mirages of our imagination, they could be subconscious ramification of facts we were exposed to, whatever the reason. Whatever the reason, it tends to be a decent reason to take heed. So first I see all kinds of news that the AI bubble has burst in China. I was unaware that they had put such a massive amount in that, but whatever. Hours later I see a splash of newscasts from all over the western world that something here is shaking too. First off there was the ‘fact’ that the fortune of Larry Ellison had dipped by $11 billion (its not a lot when you say that fast) then I see Bloomberg giving us ‘Oracle Is Near $10 Billion Share Sale at 11% Discount’, which sounds nice, if you are into those kind of things. Then about 5 hours later I see ‘Oracle, along with Alphabet, Meta, Microsoft, and Amazon, has disclosed a combined $3.3 trillion in future spending commitments.’ And suddenly the picture changes. As I personally see it, the bubble is bursting now here too and these 5 big spenders are ‘combining’ their spending (to each other) to make the bubble not happen. It is like a game of High Stakes Pot Limit Omaha (PLO) game of poker. I am not too knowledgeable on poker in general (except Aces High, not the Iron Maiden song) and we get a setting because PLO uses four hole cards (and you must use exactly two from your hand and three from the board), equity distributions run much closer together. Favored hands frequently sit at 60% to 65% pre-flop rather than dominant 80%+ leads and then one card in the middle is the Joker ‘AI’ so they are all out to get a setting of that with this poker setting that they each want to get the winning hand, but as I said it, all AI is fictive for close to 15 years, too now wonder what they are doing. Because these 5 (with Nvidia as and optional sixth) are all out in the open showing what bluffers they are and whilst we are looking we might see the common denominator in this. And the setting is ‘in future spending commitments’ because off this bubble bursts they will not be able to spend anything, the 3 trillion that they were ‘planning’ to spend will be gone with a massive amount of trillions that were always in the pot through all kind of means and suddenly no one needs the thousand or so data centres. So let that sink in.

And they are all facing more. In the first we see Meta with ‘Meta’s $25B fine left out accountability for the Cambridge Analytica data privacy scandal’ also one that I am partially on the side with Meta on that. It was ‘‘What I eat in a day’ videos landed Amelia in hospital. Now they are landing Meta in court’, so can anyone tell me how this falls on the head of Meta? (It’s a locked article) but it comes down that in the Covid era she (and others) started to share their eating habits. So, how is that Meta’s problem? Did Meta film her, or did she do that herself and was it to anyone with a medical degree or to a bunch of other near-teen people, all wanting to outdo each other on social media? This last one is not on the AI pile, but these settings tend to overlap legally and these parties are all out to get the most from their targets. (Its a legal setting) where the parties want to emulate their victim setting emulating through Donoghue v Stevenson [1932] UKHL 100 (26 May 1932), which is a famous torts case. And they all face these secondary measurements (likely Microsoft more than others) but they are all hindered down because of it. You see Microsoft is (apparently) valued at 3.77 trillion. All whilst one source gives us ‘Why is Microsoft raising $25 billion in debt when it already has $76.8 billion in cash?’ Sounds reasonable, until you see the expected debt off the books and into parties that will take the hit. It almost sounds like Party X in the late 1895 get a ‘friend’ to invest in Whaling oil, there is one big haul to get. And that friend agrees, but the dangers aware to Party X were never disclosed. Because it was June 1896 “Sperm oil prices dropped from a peak of $1.77 per gallon in 1856 to 40 cents by 1896, failing to compete with refined petroleum” and his friend now faces a decline of 78%, it was too late for him and friend X kept his head up because of all the losses he faces, well his bank did, but he scored a nice retirement. We are entering this last game of AI now. People are aware there isn such think like AI and it is merely predictive analytics, a more advanced form of it, but it is still massively dependent on data and there is the shoe that just doesn’t fit. The data is the problem mostly because of an absence of validation and verification. Also I reckon that these validation settings (whatever there is) is pushed thought several parties and they all have their own validation metrics. So there are numerous problems that many are ignoring and I saw that first hand but they are all shouting AI together and ruling up the audience. So when we go to that person who claims that those ‘believing’ that’s only idiots believe in the AI bubble are like founder Masayoshi Son and SoftBank have pivoted heavily toward artificial intelligence. They will take a massive hit soon enough, although they are also in robotics, chip design which might make it thought, but the heavy capital allocation into OpenAI might not do so well. But take the word of Masayoshi Son over me a nobody. And invest right ahead and don’t mind the shark swimming underseas, because they nibble. And it is fair to question my word who reacts to the headlines and events that the media is giving us, but ask yourself. What real reasons was there to ‘Oracle, along with Alphabet, Meta, Microsoft, and Amazon, has disclosed a combined $3.3 trillion in future spending commitments’? And how is that split up? And also where is that going? You see, the first headlines with the $100 billion mentions are optionally inspiring, but now we see “As of May 2026, there had been no further progress on the project beyond the letter of intent, with Argentina’s Economy Ministry stating that they had not received a formal application for their large venture incentive scheme.” (Source: Buenos Aires Times) so what else is in the and at present, because we were given “OpenAI and Sur Energy signed a letter of intent to explore the development of an AI data center in Argentina’s Patagonia, named Stargate Argentina. This project, the first Stargate site in Latin America, would represent an estimated investment of up to $25 billion and have a capacity of up to 500 megawatts” and as I see it, at present Argentine has about Argentina has an installed electricity generation capacity of about 44.2 GW, is that where the 500MW is coming from, and if so, why was an additional $25 billion required? Wherever you look it leads to more questions and in this game of PLO is it the intent that everyone looks at the cards, not the noise and why that noise does not seem to make sense and it is all due to secondary noise, not part of any of this, but these companies are too large to ignore this. So who is making a tally, because as I see it, none of them have the cajones to put up their own market value to this, why is that? So don’t become the patsy nesting in whaling oil when it is too late or perhaps too soon is also available, in 1820 was massively riddled with dangers. So whatever you do, ask questions and read up, because at present the entire (fake) AI setting is riddled with dangers and no one is looking beyond the headlines and into the data it is supposed to deliver.

Have a great day.

Leave a comment

Filed under Finance, IT, Law, Media, Politics

UAE making Japan bigger

OK, a little exaggerated but it sounds true, which is what the Japanese Times tells me (at https://www.japantimes.co.jp/business/2026/08/06/uae-fund-data-center/) where we see ‘UAE fund weighs $6.3 billion AI data center investment in Japan’ Japan has approximately 250 data centres, making it a top 10 player in data centres and now that the UAE is setting the funds for “Abu Dhabi sovereign wealth fund Mubadala Investment would lead the investment into a 500-megawatt project in Akita Prefecture, which may include other foreign and domestic investors, the person said, asking not to be identified because the information isn’t public. Once completed, it could become the largest data center in Japan. The talks with the Gulf state underscore growing global interest in securing critical AI assets in countries viewed as relatively insulated from geopolitical tensions.” In addition we are given “Total investment surrounding the project, including by suppliers and other companies looking to establish operations nearby, could reach as much as ¥2 trillion, the person said. A consortium of Japanese companies would likely handle construction and related infrastructure, they added. As U.S.-China tensions escalate and wars in Europe and the Middle East reshape supply chains, Japan is increasingly viewed by global investors as a stable market with relatively low geopolitical risks.”

That all makes sense and for the UAE to diversify its coffers makes perfect sense to me, so as the article ends with “Tokyo’s policy has rendered some substantial results. Major chip firms including Taiwan Semiconductor Manufacturing Co., Tower Semiconductor and Micron Technology have invested billions of dollars in the country in recent years. The oil-rich UAE, meanwhile, has emerged as one the leading global investors in AI and its underlying infrastructure. State-backed investor MGX, a joint venture between Mubadala and G42, has been a key vehicle through which Abu Dhabi bets on AI. MGX recently completed its acquisition of Aligned Data Centers, which has an enterprise value of $40 billion, alongside BlackRock’s Global Infrastructure Platform and the Artificial Intelligence Infrastructure Partnership.”

As such we might come to the conclusion that the UAE and in specific MGX is making headways in data centres and I can only speculate on the recent acquisition with BlackRock’s Global Infrastructure Partners who now have taken over 100% of Aligned Data Centers from Macquarie Asset Management, as such I reckon that there are more settings to come and I can only speculate regarding the where and the why.

So whilst you mull over this tiny gem of information, I wish you all a good night, its now 03:25, so another 240 minutes until I get to enjoy breakfast. I wish you all a marvelous day.

Leave a comment

Filed under Finance, IT, Media, Science

Casual connection

In the last 24 hours I saw two articles, they might have some casual connection and I leave that up to you to decide. First up we get an article with the staged setting of ‘Why Muslims Will Suffer Most When The AI Bubble Bursts’ (at https://www.islamicfinanceguru.com/articles/ai-bubble-muslim-investors) the first thing going through my mind is that you need to get out before disaster strikes. Get out when the going remains optional, and I would personally phrase this setting that those ‘money diggers’ make claim that you are not a pussy, make sure that he is not tying his benefit to your welfare. Because those who need your money have their own agenda. So as I read “In the late 90s, everyone was piling into internet companies. The stock market was booming, and it felt like free money. Then in 2000, it imploded. Companies worth billions became worthless almost overnight, and an estimated 100 million everyday investors lost a combined $5 trillion. Now people are worried AI could be the next bubble. And if they’re right, Muslim investors could be hit the hardest, even though most of us don’t realize it yet. Here’s why, and what every Muslim investor should be doing right now to prepare.” With additional “Over the past few years, the stock market has been on an absolute tear, and almost all of it has been driven by a handful of companies: the Magnificent Seven, Microsoft, Apple, Nvidia, Amazon, Meta, Alphabet, and Tesla. All making big bets on AI. Share prices going up isn’t itself a problem. What makes people nervous is the valuation. Take Nvidia. It’s now one of the largest companies in the world, and investors are giving it a price-to-earnings ratio of around 50. That means at current earnings, it would take 50 years of profits to earn back what you paid for the stock today. That’s an enormous amount of faith in future growth. That faith might well be justified. These companies are genuinely transforming industries. But history tells us that when the story gets ahead of the fundamentals, eventually something snaps. We’re not saying it will, but it’s worth asking: what’s the most fragile part of this whole thing? What’s the single point of failure? Because there is one.” And there is one that beckons reading (the link is at the beginning) and I agree with him. But the one thing that I take from the rest of that story is ‘acknowledge the concentration risk’ there is a downside of that, when it goes, it goes almost spectacularly (the investors don’t think out is spectacular) but I have other things against this AI setting, because from my point of view all AI is Fake AI. (Read my other works for elaboration, merely go see Google and ask: 

You should get over a dozen articles bringing this out and it merely my personal setting, but I believe that is an almost pertaining truth in all this that no one wants to acknowledge. When you come to the end of that rainbow, which did not start at a pot of gold and does not end with a pot either, you see why I believe that this is coming to an end (and right quick). Don’t get me wrong, I believe in DML (Deeper Machine Learning) and LLM (Large Language Models) these are strong tools and a lot more will be coming from this. But it al all down to the knowledge of the programmer and it just isn’t AI, not even close. So I did not give the Muslim investor much rope. I am not Muslim and I have never been an investor. Not even close, I am not even an early adopter. So whilst we now see Sam Altman in quotes all over the internet from ‘Sam Altman: ‘It also takes a lot of energy to train a human’ — a staunch defense of the cost of AI training’, so if this was real (read: true) AI, what did he have to defend? Then there is ‘“Thought It Was Satire”: Sam Altman Takes Dig At Anthropic’s New Ad Amid Online Backlash’ where we are told that:

As I see it, some people are starting to crying about the still missing ROI and that is not even getting close to the fold whilst some give us 

“AI Return on Investment (ROI) is highly debated and highly variable. While many companies report time savings and efficiency gains, a large percentage of executives struggle to see direct, bottom-line financial returns due to high infrastructure costs and a lack of proper workflow integration.” 

All whilst the ‘highly variable’ is driven towards a timeline which is (by some) decades away. As such some need to worry when they are given the image of a Cadillac, whilst they are buying an Edsel. This might not be completely accurate, but it is what I see. When the court cases are driven towards that the setting that “DMLA Submission to the US Copyright Office argues against rash “data mining laws.” They state that because a robust licensing market already exists, creators should not be forced to subsidize AI technology by allowing free text-and-data-mining (TDM) exemptions” and when you are at this point, you are likely to lose a massive bundle ofd your investment. All whilst the Tech Policy Press gives us that:

Sounds like a good place to keep your investment, because when these cases settle (I’m hopefully hoping for some coins from that equation) you are done with whatever you thought you had. But (there is always a but) there is an optional outcome and it was given to me at (https://maritime-executive.com/article/uae-plans-to-build-a-new-jebel-ali-to-bypass-strait-of-hormuz) by the maritime executive. With the headline ‘UAE Plans to Build a New Jebel Ali to Bypass Strait of Hormuz’ with the setting that UAE had left OPEC, they might be sitting pretty on some coins and that place might need investment. As oil is a commodity that the planet needs, there is every chance that your optional investment goes back from 50 years to up to 5 years with a decent spillage of coins coming your way. So when we read “The Financial Times has added to a number of reports that the UAE is planning to expand its port and freight-handling capacity on its East Coast, accessing the Gulf of Oman and bypassing the Strait of Hormuz. The Financial Times says that DP World is planning not only to build an entirely new port on the Fujairah coast, but also to expand capacity at the existing Fujairah container terminal. It is not clear what coordination arrangements DP World has made with the existing Fujairah terminal, which is operated by the AD Ports Group under the brand name Fujairah Terminals, following the signing of a 35-year concession agreement in 2017 with Fujairah Ports, which in turn is controlled by the Fujairah Al Sharqi Royal Family.” It is my firm believe that these players would accept Muslim investment and that means the setting that you might come out as a winner, because this place outside of the Strait of Hormuz would give the UAE (read: ADNOC) give a larger setting of up to 5,000,000 barrels of oil per day with the small grocery customers like India, Australia, Indonesia, Japan and China. It feel (read: me is not being an investor) like an almost sure thing and that tends to breed opportunity. And whilst we are given “Plans are already afoot to speed the completion of a second crude pipeline to parallel the Habshan–Abu Dhabi Crude Oil Pipeline (ADCOP), doubling capacity from 1.5 to 3 million barrels per day. Fujairah Ports also operates a bulk products terminal at Dibba, on the border with Oman’s Musandam Peninsula, and Dibba has also been slated for development and upgrade.” It might allow the UAE to double that doubled setting, which is personally vision, not fact based analyses. But in this, Muslims investors are likely to see another opportunity, they might move out of that Fake AI setting whilst the leaving is good. But don’t take my word for that, it is a mere view coming from academic and personal vision on IT and a personal view on where I see the world going and I have more than 500 reasons for my views and those 500 reasons are the most likely dampers on your return on investment. #JustSaying

So, have a great day today and I am on route to kill a few Metroids, because those critters are getting out of hand on my Nintendo Switch.

Leave a comment

Filed under Finance, IT, Law, Media, Science

Expect bubbles

That is what I was introduced to (really early) this morning and I saw a few articles, but one gave me an interesting option. So lets take a look. (At https://stocksdownunder.com/ai-bubble-chip-stocks-crash/) we are given ‘Is the AI Bubble Bursting? Why Nvidia, Micron and Chip Stocks Are Crashing’ it holds a lot of record, but I was taken with this setting ‘Is the AI Bubble Bursting or Just a Healthy Reset?’ With the text “Here is the honest answer: it could be either, and the truth is probably somewhere in between. The bear case is simple. Micron has more than tripled in value this year, and a run like that leaves very little room for disappointment. The bull case is that demand for AI memory and data centres is still strong, and analysts note the selling looked more like a rush for the exits than a real change in the companies’ earnings. We lean towards this being a crowded trade getting stress-tested, not the end of the AI story. But if the selling spreads well beyond chip stocks, that view needs to change quickly” (and at this point I learned that whoever was working on this is a noob and an idiot for his CSS settings as they are all over the place) But that is matter for another day. The “It could be either” and a third setting was the one I referred to a few days ago when simply Wall Street put out an unsigned piece that Palantir could be overvalued for well over 20%, as such this market has some people in it that would like to short stock as that is where their dollars come flying. And as we see in the article “Investors simply pay less for today for profits that may not arrive for years.” And as I see it, some investors are not beyond shorting stock if it fuels their profits, so a third reason is found. I am still on the side of the AI bubble shorting, but n that case a healthy reset of trillions is not out of the scope of things and the marshmallow field of fictive unicorns is rearing its ugly head that comes with the “late arrival of profits” and now that the investors are wondering what they got into, some will see that they are fueling a stock market that cannot survive delay upon delay and with AI not yet existing that is where it is all heading. So it is time to get another view and we see this in Clean Technica (at https://cleantechnica.com/2026/06/24/trillion-dollar-ai-bubble-on-verge-of-popping/) where we see ‘Trillion-Dollar AI Bubble On Verge Of Popping?’ And I am not adding it, because this is in part the view I have, what we see is “Yann LeCun, one of the “Godfathers of AI,” is one of the notable people who think the industry has been far too overhyped and misunderstood. He’s been pointing out that AI costs could be much higher than the amount of money customers are willing to pay for it.” It comes (also) with “Labs like OpenAI and Anthropic are going to have to increase prices, they’re going to have to cut costs, or there’s going to be a big bubble explosion,” and ““In their pursuit to boost productivity, become less reliant on human labor, and reassure investors that they’re riding the cutting edge of tech, some nagging issues are cropping up,” Futurism adds, and “over-relying on AI can prove disastrous for organizational knowledge, the critical business insights companies need to make strategic decisions.”” This is the setting that is actually fueling both the bubble burst as well as a healthy reset all at the same time and I reckon that for OpenAI, Anthropic, Grok and Microsoft that will most likely happen in the least interesting time and they will all ‘suffer’ for it, so consider when this bubble loses $4,000,000,000,000 – $5,000,000,000,000 (writing the word trillion makes it trivial) because that is likely to happen and the market is figuring out what I saw over 1-2 years ago, when you realise that all AI is fake, it is easy and let there be no mistake, all AI is fake. You see, what we are seeing is Deeper Machine Learning and Large Language Models and these are great tools and they will create markets for themself, but the people are expecting AI and that is just not true. So as AP News gives us “The tech-heavy Nasdaq composite fell 110.40 points, or 0.4%, to 25,476.64. A 2.3% drop in Microsoft was the heaviest weight on the market. Oracle slumped 4.6%. Many large tech companies have been behind Wall Street’s record-setting run throughout the year, but analysts have warned their valuations may have become stretched.” I personally reckon that someone is likely playing a stock short game with both Oracle and Palantir. You see, no matter how you slice it, the proper Data needs for DML/LLM solutions require data technology and these two are refined into the core of that and optionally there is Snowflake as well, but it might not yet be large enough to get the attention of the stock shorting DoDo’s (lets call them that).

Jawlah, a prominent Arabic digital media platform and news organization focused on venture capital (VC), startups, and the entrepreneurial ecosystem in Saudi Arabia and the broader MENA region (Middle East/ North Africa) gives us (at https://jawlah.co/en/59212) where we see ‘Fears of an AI bubble burst after a sharp tech stock sell-off’, which I reckon is fair enough. But the interesting part is where we see “The decline followed a near-800% surge in Micron’s stock over the past year, driven largely by rising demand for memory chips needed to run AI globally — gains some analysts believe may have overestimated expected returns”, as well as “Gil Luria, head of technology research at D.A. Davidson, explains the volatility: “The market swings between a wave of optimism that AI will change everything and renewed skepticism that it is just an expensive bubble whose returns do not justify the current spending.”.” And I am here in opposition, it is not “renewed skepticism”, it is the mere setting that those willing to hand out trillions should never have been so optimistic without proper case files and validation, so whilst they might get their cash back in 2045 when actual AI comes into play, the rest until then will be massively overvalued.  As I, as a non-believer, see it, someone listened to a sales person with the mindset of a second hand car salesman that stated “Look, we have AI” and the rest followed like crazy to get those coins rolling their way and now we are optionally seeing the start of an AI bubble. I am trodding carefully because there is disagreement whether it is an actual bubble popping. I reckon it requires an actual econometrist to call that for real and I ain’t one of those actuary types (nowhere near).

What we see is that we are given “it has erased approximately $2.7 trillion in market value across AI-linked companies”, all whilst the reasoning is “massive debt-funded data center expansions, mounting hardware costs, and growing investor scrutiny over artificial intelligence’s actual return on investment” which (as I personally see it) is only partially true. As I see it, the data sovereignty in Europe and the Commonwealth is setting the drain on the Return on Investments (ROI) towards these massive debt-funded data center expansions and that will hit business in the United States a lot harder than anywhere else. You see the United States has over 4,000 data centers. So how many are still under debt? And when a response group of over 700 million people walk away from that, with an additional optional population of up to 2.7 billion people (that is the complete Commonwealth), so it will not be that much, but I reckon at least 50%, that is 4,000 centers that will now lose close to 2 billion people (or 2,000 million), so where is that unused potential going? That is what I saw almost a year ago (actually a lot earlier, but until President Trump come, most people let the states quo continue) and that has now changed. So as others players (like DayOne) and there is someone in Sweden who saw this coming a few years ago and put his money where his thoughts were. I forgot that players name, but they are likely to make massive gains. All out off the hands of the United States. That part is not represented in any of these articles, but it is a factor in all of this.

So, we are expecting bubbles and I reckon a few other setting will rear its ugly heads, but the markets will all attribute this towards bubbles, because some is massively unhappy to attribute the other losses towards an US Administration that should have known better, but that is merely me looking at other factors in all this. The larger issue in all this is that some solutions are likely to be rather good and I hope that they are allowed to continue, because investors and speculators will want their returns at whatever expense they can get and some will suffer because of that greed driven taint in all this. But I might be the next village idiot in all this. Just like that seer in the 3rd century that saw large walls of stone with thousands of people and it was written off as a lying loon (he saw the Altiero Spinelli building in Brussels) but that is a story for another day.

So whatever you do, don’t rush into or out of anything without clearly seeing the ramifications. Have a great day today.

Leave a comment

Filed under Finance, IT, Media, Politics, Science

Bleeding on the spot

That is at times the setting, we tend to ignore it, we laugh, we giggle, and sometimes we cry. If it is your own body, you will likely panic. So as I saw Tom’s Hardware (at https://www.tomshardware.com/tech-industry/artificial-intelligence/cerebras-files-for-ipo-company-remains-unprofitable-despite-20x-revenue-growth) give us ‘Cerebras files for IPO — company remains unprofitable despite 20x revenue growth’ I tend to frown. There are settings with little profit (like the Big Mac for $1.95) which at 20 times still becomes a decent amount (all $6 of them), we get that other factors that remove profit margins, but when the setting becomes “Bleeding money at a rapid rate” it becomes a worry. You see, the business plan makes sense or is a hail Mary (not unlike the Macintosh Performa) this is an intentional setting I am giving, because that Hail Mary became the PowerMac and then the G4 and G5. These were the systems that put Apple on several maps and from there the big wins became visible. A Hail Mary that worked. But here we are given “Cerebras, the supplier of wafer-scale AI processors, has filed for an IPO for the second time after it cancelled such plans due to its ties with G42, an Abu Dhabi-based AI company backed by sovereign wealth fund Mubadala, last year. Financial results disclosed as part of the filing reveal that Cerebras appears to be one of the fastest-growing AI hardware companies right now. However, 86% of its revenue comes from two customers, and the company is bleeding money.” From this limited information I would gather that the business plan is highly likely flawed. And we are given that the 86% comes from just two customers (G42 and Mohamed bin Zayed University of Artificial Intelligence, MBZUAI). Now I would go with the Business plan, but there might be reasons for this and the settings that AI processors give could still be a solution if these two clients put in the considerable work (no critique on the two trendsetters). As we see that “The remaining 14% of revenue is generated by a fragmented base of smaller enterprise, government, and cloud customers, but none contribute enough individually to reduce Cerebras’ heavy reliance on its top two clients. More recently, Cerebras inked agreements to supply its AI hardware to Amazon Web Services and OpenAI, which will diversify revenue streams for the company.” But the larger option is gaining traction. Now for the most we can ignore the fact that they are American (which is at present never a good selling point), but they  are also in Toronto and Bangalore. The issue is that they are no threat to Nvidia and they don’t need to be, the idea is that they could skim the market and take up traction pretty much anywhere. I reckon that they have done that, but there is the option that they could optionally feed data centers in China, Saudi Arabia and the UAE, if that works and they could get the first one in these places, they are likely to gain several other corporations and locations for implementation. The reasoning I have is that there are several sounds from customers that they have a lack of processors, so are they tapped? It seems so as we see “Cerebras has a massive $24.6 billion backlog (including the $20 billion OpenAI deal), which provides strong demand visibility. The company expects to recognize approximately 15% of this revenue within the first 24 months through December 31, 2027, 43% during months 25 to 48, and the remainder thereafter. Still, Cerebras warns that converting this backlog into revenue depends on the manufacturing capacity of its partners, infrastructure deployment, and power availability.” It makes me wonder why the quote “Bleeding money at a rapid rate” was given. So as we see “Cerebras recorded a $363 million gain from a change in the fair value (and extinguishment) of a forward contract liability: the company had a financial obligation whose value was reduced, which allows it to book that reduction as income. If the value was not reduced, the company would be unprofitable. In fact, Cerebras’ operating losses totaled $145.9 million in 2025.” But even so, as I see it (with my lack of economy studies) thematic doesn’t seem to add up and my mind goes back to the business plan. It is my simplistic mind that goes with the setting that Cerebras either has a product that works or they have not. If they do, the client has to pay and there are no freebees in this market, you do that if the product is shoddy, and the salesperson either deals with the buyer correctly, or they don’t. It is my rather simplistic setting of customer service, “we have a product and we would love to have you as customer, yet, our product is not free”, it will rock your world (for a price) and within that setting (and the right business plan) Cerebras should do just fine. As such I don’t get the setting we see. So as we are also given “Cerebras postponed its IPO plans in 2024 after a national security review examined its ties with Abu Dhabi-based G42 amid concerns about potential foreign access to advanced AI processors. G42 is both a customer and investor of Cerebras, which controls a 1% stake in the company that it acquired for $40 million in 2021.” This is an issue as it involves 50% of their customer base and what is this “potential foreign access to advanced AI processors”? Is this another American setting (not unlike their stance towards Huawei)? You see China is sized at 1.413 billion, as such it is over 4 times the size of the USA, the United States can either play nice or go down with the ship they are sinking themselves. Cerebras could go towards the EU as well as India and partially fund the data centers there and get longer lasting revenue, but that is almost the only options that are there. This market is getting saturated and it is not a market that has time and options for prima donna’s, this is my simplistic view. So as the article ends with “Cerebras has not specified an official fundraising target in its IPO filing, but current market expectations point to a roughly $3 billion raise. This is significantly higher than earlier $1 billion plans, which reflect the company’s rapid revenue growth and the scale of its AI infrastructure ambitions.” It also signals that the ‘bleeding effect’ is a temporary setting, depending on how the IPO evolves. Yet as I see it, the IPO has a lot less chance of being successful as long as the “Bleeding money at a rapid rate” vision is in place. But as I see it, enlarging their customer base precedes the need for an IPO, because no I matter how good the IPO is, it is facing slaughter when the customer base is set to two. But as I stated, my lack of economy might be the ruling red herring here. 

And whilst I leave you with this article and a few hidden hints, I will go and look what happens to Cerebras before June, May it have a nice time.

Have an interesting day today (‘great’ is oversold too much, even by me).

Leave a comment

Filed under Finance, IT, Media, Science

The Bull what?

I was confronted with an Oracle article this morning, it came with the complements of the Insider Monkey (at https://www.insidermonkey.com/blog/oracles-orcl-backlog-drives-its-bull-thesis-according-to-analysts-1726682/). The article ‘Oracle’s (ORCL) Backlog Drives Its Bull Thesis According To Analysts’ which might be a conundrum, so lets take a look. We are given “The major factors in the firm’s bullish thesis on ORCL are its massive backlog and its ability to cater to increasing AI investments in the US. Oracle has a remaining performance obligation (RPO) of $553 billion, which offers good visibility into the company’s future earnings.” I would go with that a backlog gives stock and future of a company value, but that might be an oversimplification. And $553,000,000,000 is nothing to sneer at. It is seemingly more than the overall business that several nations have and in this case it is more then Norway gets on an annual level. So I would go with that, but what is a bullish thesis? 

Well, in short “A bull thesis is a structured argument supporting the belief that a specific stock, sector, or the overall market will rise in value, driven by positive catalysts like strong earnings, innovation, or economic expansion. It focuses on growth potential, such as AI-driven productivity, high revenue backlogs, or increased market share.” (Source: Simply Wall Street).

So I had it correct the first time over (a few days ago). There was nothing new under the hot sun, but the next bit ‘surprised’ me a bit. It was “The analyst also pointed out that a major risk in the bull thesis is the customer concentration. A large part of this backlog comes from OpenAI. OpenAI intends to invest a total of $600 billion in computing power by 2030. Previously, in October, OpenAI CEO Sam Altman said the company could spend up to $1.4 trillion on infrastructure by 2033. One month ago, BNP Paribas analyst Stefan Slowinski commented on how this particular risk is now reducing for Oracle Corporation (NYSE:ORCL):” So in short, most of the backlog comes from OpenAI, if OpenAI fails (not a weird thought) Oracle stumbles as would be the case, so the backlog is due to mostly one customer and that is a rusk. How big a risk remains to be seen. The people wanting OpenAI to succeed are numerous and ‘THEY’ would be reducing the risk like the metal dealer reducing the risk of riveting and downplaying potential dangers. This went well before the Titanic saw the shores of the ocean (bottom of the sea), but what happens afterwards? Now, riveting is largely supported, there are whole fleets still out there based on riveting. But what happens when the next big thing comes (like welding), so that is where we are right now. But on the horizon we see Google DeepMind, Anthropic, Meta, DeepSeek and something called Cohere. I believe Oracle is in a good space as whatever comes next will require a system that deal with data and I believe that the only competitor here is Snowflake. As such yes, there is a risk to (what some call) the Bull thesis, but the risk is seemingly small as nothing can match Oracle and Snowflake can only partially cover Oracle (as I see it) and I have some reservations on BNP Paribas analyst Stefan Slowinski as BNP Paribas and OpenAI have a multifaceted relationship involving financial analysis, infrastructure, and competition within the AI landscape and this article dos not bare this out. But in that setting we also fail to see the setting that ‘SoftBank Secures $40 Billion Loan to Fund $30 Billion OpenAI Investment’ (source: TradingView) this matters as there is a backlog and they still need loans/investment funds? And the second setting is given to us (at https://www.nssmag.com/en/lifestyle/44761/sora-openai-shutdown) where we see ‘Understanding OpenAI’s U-turn on Sora’ where we see “The development team of Sora, the artificial intelligence software by OpenAI that allowed users to generate realistic videos from a simple prompt, recently announced the shutdown of the app. It is a sudden and highly significant change, one that is expected to produce notable effects in the technology and entertainment sectors, with repercussions that could extend well beyond the U.S. market. The shutdown of Sora is not relevant only for the company led by Sam Altman, but also for other players active in the field of generative AI applied to video production. Google, for instance, now finds itself in an advantageous position in this area, with the concrete possibility of consolidating its leadership in the generation of realistic AI-based videos – thanks to its tool Veo.” So some will see this as a boost to Google (DeepMind) but this happens before these tracks became financially viable (read: paying off) and these elements will create some sort of minor shockwave. The problem is that 3-4 shockwaves can create a massive customer turnover (like towards a competitor) and even if it doesn’t ‘damage’ Oracle, it might hurt prospects in that near future. Consider that this backlog of $553 billion reduces it to a mere $125,000,000,000 Still a large number, but that is when it starts raining men on Wall Street (aka: watch out below).  All elements overlooked in Insider Monkey and the non-Chinese media is not too bitty in the DeepSeek settings. So we are mostly unaware how their next version of its engine is. All elements that will influence the view on Oracle. I still have faith that Oracle will pull through successfully, but these pesky investors are at present more jittery than a room full of roaches as you turn on the lights. It might not be the best setting for a long term ‘understanding’ and that is something Oracle has to deal with. 

Have a great day, I am now 120 minutes from breakfast, although if I was in Vancouver I could enjoy another lunch in the Nightingale like a Cache Creek Beef Tartare, yummy.

Leave a comment

Filed under Finance, IT, Science

Bank on this

Early this morning the Khaleej Times alerted me to a story (any https://www.khaleejtimes.com/business/finance/united-arab-bank-posts-45-surge-in-2025-profit-as-assets-and-income-climb). Now we all assume that banks make all the money, but that is not the whole story. You see under Sharia law banks have ‘limitations’. Or perhaps better stated “Islamic banking operates under Shariah law, primarily prohibiting interest (aka: riba), excessive uncertainty (aka: gharar), and gambling (aka: maisir). Key rules include mandatory asset-backing for transactions, sharing risks and profits between bank and customer, and investing only in ethical, halal businesses. Common structures include Murabaha (cost-plus financing), Ijarah (leasing), and Musharaka (joint venture).” Are settings that an islamic banks need to adhere to. So when you see these ‘limitations’ and then the Khaleej Times gives us ‘United Arab Bank posts 45% surge in 2025 profit as assets and income climb’ we might see another side, mainly the side of how well the UAE is doing at present. The subtext “A key highlight of the year was the Sharjah-based lender’s successful Dh1.03 billion rights issue, which increased the bank’s paid-up capital by around 50%” with the added “The bank recorded a net profit of Dh438 million for the year ended 31 December 2025, up from Dh301 million in 2024. Total income climbed 31 per cent to Dh797 million, fueled by what the bank described as “strong momentum” across its core businesses. Non-interest income surged by 56 per cent, while net interest income rose 24 per cent.” this is what I call a massive boost to the UAE economy, so whilst you are getting fed up (tired too) on how bad the United States is doing, you see here an example on how it could be done and people better consider the fallout, because at present any dollar (Euro’s and Pounds too) that aren’t currently being invested in Europe, America, Commonwealth, Europe and a few other places are likely being invested in the UAE. I don’t know how well Saudi Arabia is doing, but it is doing a lot better than Europe. So when we get to “Chairman Sheikh Mohammed bin Faisal bin Sultan Al Qassimi said 2025 marked a pivotal year for the bank as it celebrated its golden jubilee and unveiled a refreshed brand identity. “It proved to be a transformative period for UAB, reinforced by decisive strategic initiatives and robust financial performance,” he said. “Operationally, the Bank delivered solid profitability, supported by disciplined execution, prudent risk management, and enhanced operating leverage.”” You know that they are doing it right and a strong willed and able minded board of directors was at the head of that setting. I reckon that the western world will eagerly look at the reports of SAMA (Saudi Central Bank) and the CBUAE (Central Bank of the United Arab Emirates). Because as I see it, the 2025 results are merely the beginning and if my predictions hold firm, the Western world (and its banks) will come under the spell of ‘Dry Well psychoses’ soon enough and when the opportunities of Wall Street dry up because of the economy in the United States, these two countries will get a lot of opportunities ‘handed’ to them and whilst we might worry about the Influence they will gain, these ‘new’ banks will have to adhere to Sharia law and the laws of the land, which prohibits them from making certain steps. So while we might stop at “UAB also reported healthy asset quality, with a net reversal of impairment charges amounting to Dh51 million, translating to a cost of risk of –41 basis points. The bank attributed this to strong recoveries and its “robust risk framework.” Its cost-to-income ratio improved to 46 per cent, down from 52 per cent the previous year, while return on shareholders’ equity stood at 16 per cent.” Banks on a global setting haven’t seen this since the post-WWII Golden Age, which went from 1950–1973, as such the last really successful ‘boom’ period was 53 years ago, so you better bet on the non-Islamic banks taking notice at present. Whilst President Trump will be wondering where the money is going to and he might wonder why no one is betting on his ‘beautiful’ bills, I get the notion that banks might want to vacate towards the settings of SAMA and the CBUAE at their earliest convenience, especially as this comes with an almost certain guarantee for return on their investors. As such I noticed the settings we are given and I wonder how well ADNOC is doing in all this, because their profits go somewhere, don’t they and as I see it, the CBUAE is a safe bet to consider. 

Have a great day today, Perhaps tomorrow I get to write on some gaming IP. 

Leave a comment

Filed under Finance, Politics

The age of uncertainty 

I thought that times were changing, see I invoked some were invoked on me, or something of that nature. Two days ago I started a new script, I call it “Just A Game” which gives me the letters J.A.G. (no relation) but the setting was created to scare the jibbers out of the NSA, GCHQ and related organisations. Set to that I created a few kinks to get the setting of drama going and it is a film script, not some autography to scare three to four people. They get enough real scares for that, as such I wouldn’t be able to hold a candle to the real nightmares.

Then I got introduced to (what I am fathoming to be grifters in media) as I got exposed to ‘Oracle stock slips after insider sale filing as openai-linked spending stays in focus’ where we see “Oracle shares fell 0.4% to $197.27 in early trading on Monday after a company officer disclosed a planned share sale, with investors still wary about the cost of the software maker’s push to expand AI-related cloud capacity.” It is important to say that no lies were told, but as I see it, when we see “That scrutiny has been sharpest around Oracle’s ties to privately held OpenAI, where investors lack the same visibility into funding and cash burn that they get with public companies, analysts and traders said. (Source: Benzinga) A Form 144 filing accepted on Monday morning showed Oracle officer Mark Hura proposed selling up to 15,000 shares, with an aggregate market value of about $2.95 million, through Fidelity Brokerage Services. Form 144 is the SEC notice used when company “affiliates” — insiders and certain large holders — plan to sell shares under Rule 144, which sets conditions for selling restricted or control stock into the public market.” It feels like someone is trying to undermine the power of Oracle. Then we get ‘Oracle Shares Plunge Amid Mounting Concerns Over AI Strategy’ (source: Ad Hoc News, Germany) where we are given “Oracle Corporation is facing one of its most severe market downturns in decades. Since reaching a peak in September, the technology giant’s stock has plummeted by more than 40%, putting it on track for its worst quarterly performance since 2001. This dramatic sell-off is fueled by investor apprehension over soaring capital expenditures and a wave of insider selling, raising fundamental questions about the sustainability of management’s aggressive artificial intelligence investment plan. A primary catalyst behind the market’s negative reaction is the explosive growth in Oracle’s capital investments. The company’s capital expenditures tripled year-over-year in its second fiscal quarter, reaching $12 billion. In response to this surge, management significantly raised its annual forecast for such spending to a staggering $50 billion.” There is no lie, but in September, stock was $328 and it is lower now, but that is the setting of a market in motion, over the last day it was switching between $194 and $195, as such there is no real dip in intent, and the $328 was true, but the day before it was $241, but the article doesn’t spell that out, does it? And two days after the spike it had ‘dwindled’ to $292, and after the quarter that followed the stock would reset itself to $198, as such it seems like ‘doom speak’ and I have a problem with that, Oracle has proven itself time and time again and when true (say: real) AI arrives, it will only function under the data armour that Oracle provides, most others are wannabe’s trying to do what Oracle and Snowflake successfully do. As such we are in a stage of uncertainty, the media is used to fuel digital dollars, fueling influencers and wannabe prophets of doom times. Even as I recognise them, they gave me an idea of an old setting. You see we have been through this before in the age of the bards. They gave us the doom speak, the white knight and the victory, but that setting is now applied to economic fortune telling, so the more things change, the more they stay the same.

And in all that ruckus, I am trying to keep my brain afloat (on ice water) and unburdened by noise of economic influencers. I try to avoid most economic news, but when the attack on Oracle started, I just had to step in. There were more articles, but these two set the marker quite nicely. And it is important, because the media no longer does what it was designed to do, it now prevents itself from drowning whilst chasing digital dollars. Lets hope that the age of uncertainty fades quickly, America has its own set of losers trying to bank in on that and with a non-functioning media, we need all the help we can get. Have a great day today.

Leave a comment

Filed under Finance, IT, Media